Top 10 Index Funds in India: How to Compare and Choose (2026)
Fund data in this article, including expense ratio, AUM, tracking error and returns, was checked in early September 2026 using fund house disclosures, AMFI data and fund-tracking platforms. The comparison uses Direct Growth plans wherever available to keep the comparison consistent. Since fund metrics can change over time, the figures below should be treated as a snapshot and not a permanent ranking.
Check the latest factsheet and scheme details before investing. Past performance does not guarantee future returns, and index funds are not risk-free. The right fund for you will depend on your investment goal, time horizon and risk appetite.
Let’s get started right with the basics.
What is an index fund and how does it work?
An index fund is a mutual fund that aims to track a market index such as the Nifty 50 or BSE Sensex. It invests in the companies that make up the index and broadly follows their weightings. Unlike an actively managed fund, there isn't a fund manager trying to pick stocks and beat the market. The goal is to deliver returns that closely follow the index, after accounting for expenses and tracking differences.
Because there is less active stock-picking and research involved, index funds generally have lower costs than actively managed equity funds. They are also relatively easy to understand. You can see which index the fund tracks and what companies make up that index, giving you a clear idea of where your money is invested.
Learn more: SEBI’s introduction on mutual funds
How we selected the top index funds in India
There are plenty of index funds to choose from, so we didn't look at returns alone. We considered a combination of cost, tracking efficiency, fund size, benchmark, fund-house experience and risk.
Expense ratio
Lower costs can make a difference over a long holding period, so we favoured Direct plans with competitive expense ratios. But the cheapest fund wasn't automatically treated as the best option. Tracking efficiency, fund size and the underlying index also matter.
Tracking error and tracking difference
An index fund is designed to follow its benchmark as closely as possible. A lower tracking error or tracking difference generally means the fund has stayed closer to its index. We therefore considered tracking efficiency alongside the expense ratio rather than looking at the fee in isolation.
Fund size and liquidity
A larger AUM can indicate that a fund has attracted a substantial investor base and has an established operating history. However, AUM alone doesn't determine how well a fund tracks its index, so we considered fund size along with tracking efficiency, costs and the fund's track record.
Historical performance
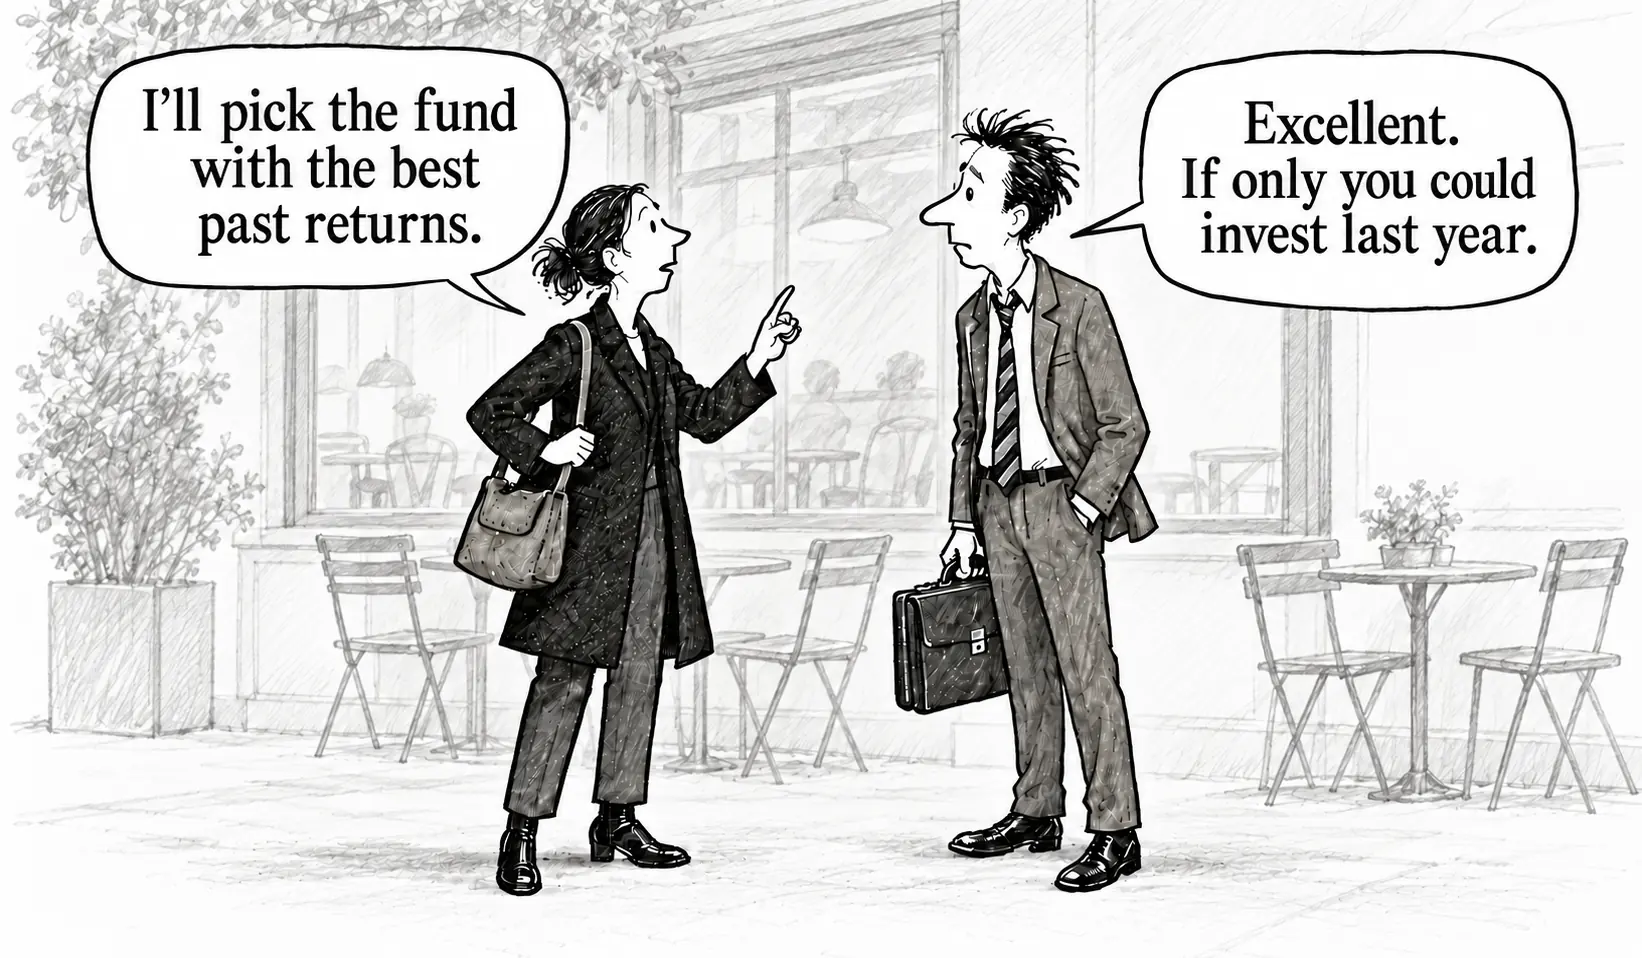
Historical returns were considered as one factor, not as a reason to automatically favour a fund. A fund isn't included simply because it happened to deliver a higher return over the most recent period. Past performance also does not guarantee future returns.
Fund house track record
We considered the fund house's experience in managing index funds and its ability to track benchmarks consistently. Operational processes matter in passive investing because even small differences from the benchmark can add up over time.
Benchmark index
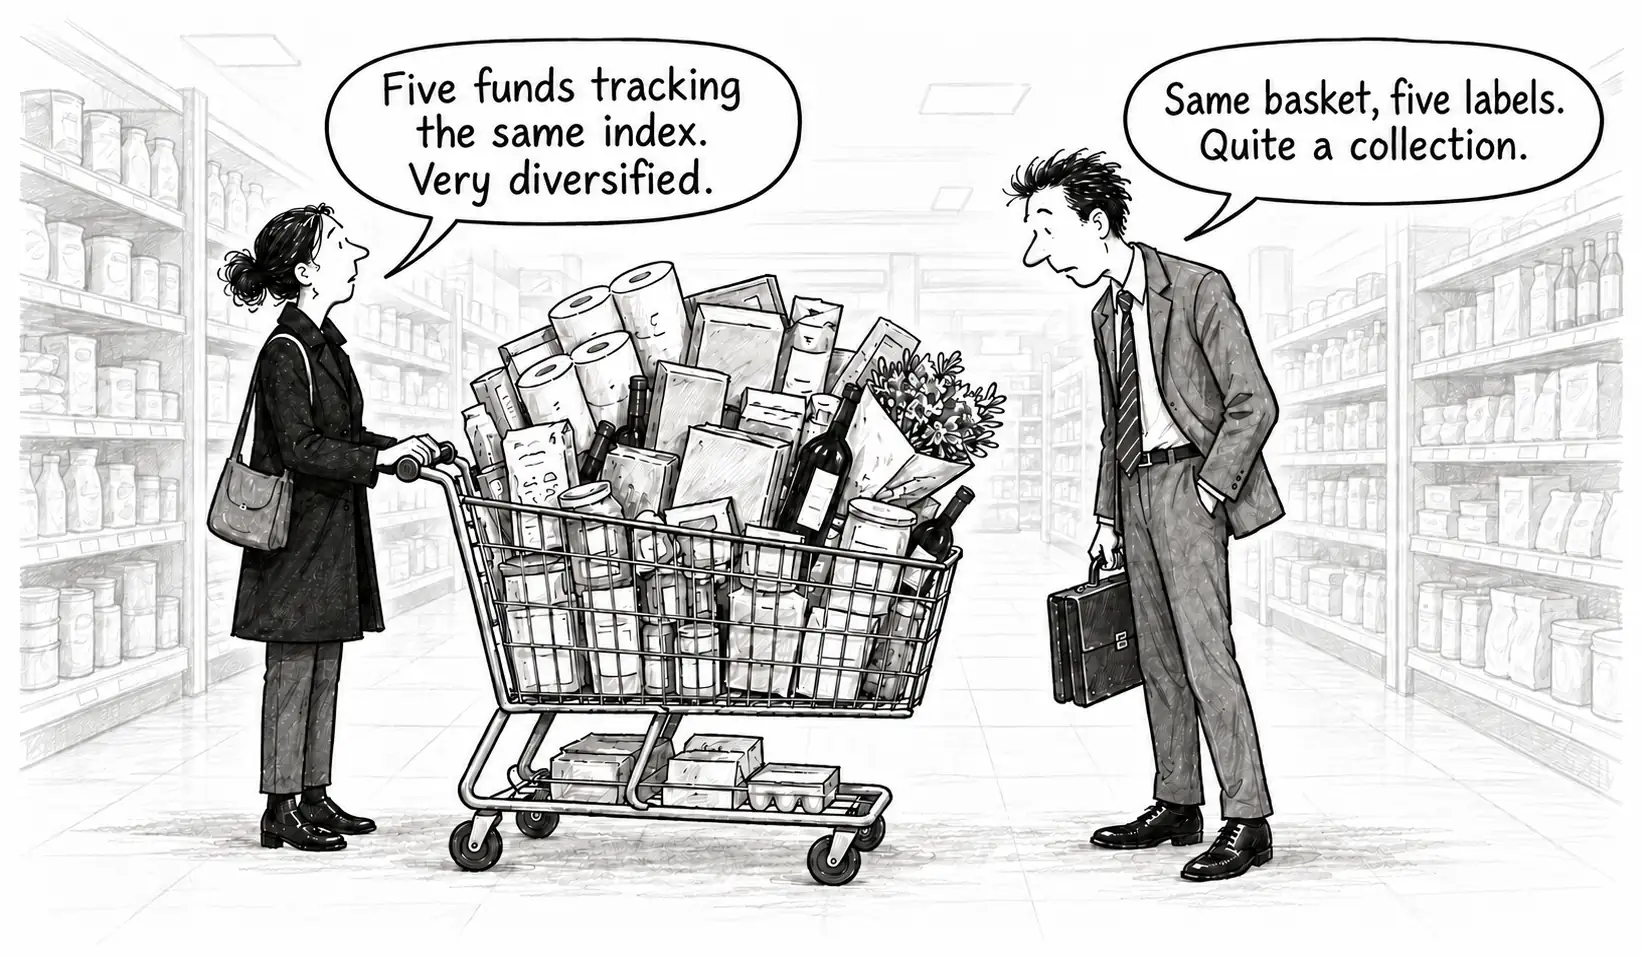
We included funds tracking different benchmarks, including the Nifty 50, Sensex, Nifty Next 50 and Nifty 500. This gives investors a choice of different types of market exposure rather than ten funds that essentially do the same thing.
Investment risk
All the funds discussed above are equity funds and are exposed to market risk. The underlying index matters too: a broad large-cap index and a mid- or small-cap index can behave very differently during market cycles. These funds may therefore not be appropriate for money you expect to need in the short term.
Top 10 best index funds in India for long term investment
If you're looking for a simple way to invest in the broader market, index funds can be a useful starting point. But there isn't one index fund that is automatically the best for every investor.
The table below compares 10 established index funds across the Nifty 50, Nifty Next 50, Sensex and broader-market benchmarks. The comparison focuses on factors such as cost, tracking efficiency, fund size and historical performance. All figures are for Direct Growth plans, wherever available, and the data should be treated as a snapshot rather than a permanent ranking.
A quick note on that last column: Under SEBI's Riskometer, equity index funds can fall into the "Very High" risk category. But that doesn't mean every fund on this list is equally volatile in practice. A Nifty 50 fund, for example, tracks India's largest companies, while a Nifty Next 50 or Nifty 500 fund gives you a different mix of companies and can behave differently during market cycles.
Now let's look at each fund a little closer.
UTI Nifty 50 Index Fund is one of the larger and more established funds tracking the Nifty 50. Its long track record and relatively low tracking difference make it a popular choice among investors looking for a simple core equity holding.
HDFC Index Fund - Nifty 50 Plan is managed by one of India's largest AMCs and gives investors straightforward exposure to the Nifty 50. Its expense ratio is slightly higher than some of the lowest-cost options on this list, so it's worth comparing the cost alongside its tracking efficiency.
ICICI Prudential Nifty 50 Index Fund combines a relatively competitive expense ratio with a long track record of tracking the Nifty 50. It may appeal to investors who want broad exposure to India's largest companies without taking on the additional concentration of a sector-specific index.
SBI Nifty Index Fund is another established Nifty 50 option, with a relatively low expense ratio among the larger funds in this category. That makes it worth considering for investors who are particularly conscious of keeping the ongoing cost of their index investment low.
Nippon India Index Fund - Nifty 50 Plan stands out for its low expense ratio. Its AUM is smaller than that of some of the larger Nifty 50 funds on this list, although the fund has been around long enough to have an established track record. Investors should still look at its latest tracking data and costs before making a decision.
Motilal Oswal Nifty 50 Index Fund is a relatively newer and smaller fund compared with some of the established names above. Its expense ratio is competitive, but its shorter track record means there is less historical data to assess. Investors should pay particular attention to its latest AUM, tracking efficiency and performance before investing.
HDFC Index Fund - Sensex Plan tracks the S&P BSE Sensex, which consists of 30 large and established companies listed on the BSE. The Sensex and Nifty 50 have significant overlap and have generally delivered similar broad-market exposure, although their constituents and weightings are not identical.
UTI Nifty Next 50 Index Fund and ICICI Prudential Nifty Next 50 Index Fund track the Nifty Next 50, which represents the 50 companies ranked immediately after the Nifty 50 in the relevant Nifty index hierarchy. These companies can have a different risk and return profile from the Nifty 50, so investors should not treat a higher historical return as a reason to automatically prefer them.
Motilal Oswal Nifty 500 Index Fund provides exposure to a much broader segment of the Indian equity market, covering large-, mid- and small-cap companies through the Nifty 500. That can make it relevant for investors who want broader market exposure in a single index fund, while also accepting the additional volatility that can come with exposure beyond large caps.
Different types of index funds in India
Index funds can look quite different depending on the benchmark they track. While Nifty 50 and Sensex funds focus on large, established companies, other index funds give you exposure to the next tier of companies, specific sectors, international markets or even debt. Here's a quick look at the main types available to Indian investors.
Nifty 50 Index Funds
Nifty 50 index funds track the Nifty 50, an index of 50 large and liquid companies listed on the NSE. Because of its broad exposure to established large-cap companies, it is commonly used as a core equity allocation.
Sensex Index Funds
Sensex index funds track the S&P BSE Sensex, which consists of 30 large and established companies. There is significant overlap between the Sensex and Nifty 50, so their long-term performance can be similar, although the two indexes have different constituents and weightings.
Nifty Next 50 Index Funds
Nifty Next 50 index funds track the 50 companies that rank immediately after the Nifty 50 within the Nifty index structure. They can have a different risk and return profile from the Nifty 50, and investors should expect potentially higher volatility rather than assuming they will outperform.
Nifty 100 Index Funds
Nifty 100 index funds combine the Nifty 50 and Nifty Next 50, giving investors exposure to 100 large companies through a single index. This provides broader large-cap exposure than investing in the Nifty 50 alone.
Mid Cap and Small Cap Index Funds
These funds track indexes such as the Nifty Midcap 150 and Nifty Smallcap 250. They provide exposure to companies outside the large-cap segment and can offer higher growth potential, but they also tend to come with greater volatility and downside risk.
Sectoral and Thematic Index Funds
Sectoral index funds focus on a particular industry, such as banking, IT or pharmaceuticals. Thematic funds follow a broader investment theme, such as consumption or ESG. Because they concentrate exposure in a particular area of the market, they can carry more concentration risk than broad-market index funds.
International Index Funds
International index funds track overseas benchmarks such as the S&P 500 or Nasdaq-100. They allow Indian investors to diversify beyond domestic equities, although returns are also affected by currency movements, international market conditions and the specific benchmark being tracked.
Debt Index Funds
Debt index funds track fixed-income benchmarks, such as government bonds or corporate bond indexes. They can have lower volatility than equity index funds, but they are not risk-free. Interest-rate movements, credit quality and changes in bond prices can affect their returns. Their return potential is also generally different from that of equity index funds.
Index funds vs ETFs: What is the difference?
AMFI explains that ETFs are traded on stock exchanges and held in dematerialised form, whereas index mutual funds can be purchased directly from the fund house or through investment platforms without requiring a Demat account.
For investors making regular monthly investments, index mutual funds can be simpler because SIPs can be automated and units are purchased at the applicable NAV. ETFs may appeal to investors who already have a Demat and trading account and want the flexibility of buying and selling during market hours. However, the lower expense ratio of an ETF does not automatically mean it will be cheaper overall, since brokerage, bid-ask spreads and other trading costs can affect the actual cost.
Learn more: AMFI on Index funds and ETFs
How to choose the right Index Fund for your portfolio
Choosing an index fund isn't just about finding the fund with the lowest expense ratio or the highest past return. Start with what you're investing for, how much volatility you can handle and which part of the market you want exposure to.
- Define your investment goal: Your time horizon should influence the type of index fund you choose. A retirement goal that is 20 years away gives you more time to ride out market fluctuations than a financial goal you need to meet in three years.
- Assess your risk appetite: Nifty 50 and Sensex funds focus on large, established companies, while Nifty Next 50, mid-cap, small-cap and sectoral funds can have a different risk and volatility profile. Don't choose a more volatile index simply because it has delivered higher returns in a particular period.
- Select an appropriate benchmark: Think about what you want your investment to cover. A Nifty 50 or Sensex fund can provide large-cap exposure, while a Nifty 100 or Nifty 500 fund gives you a broader basket of companies. If you're looking beyond Indian large caps, international or other specialised indexes are also available.
- Compare costs and tracking efficiency: If two funds track the same index, compare their expense ratios as well as their tracking error and tracking difference. A lower cost is useful, but what matters is how closely the fund has actually followed its benchmark after expenses.
- Decide between SIP and lump sum investment: A SIP lets you invest a fixed amount at regular intervals instead of putting all your money into the market at once. This can be convenient for investors with a regular income and also means you buy units at different market levels over time. Lump-sum investing involves putting in a larger amount at one time and may make sense when you already have surplus money to invest and are comfortable with market fluctuations.
Benefits of investing in Index Funds
Index funds are popular largely because they keep things simple. They generally have lower costs than actively managed funds, provide diversification through a basket of securities and make it easy to know which benchmark you're investing in.
There's also less dependence on a fund manager's stock-picking decisions. Instead of trying to identify the stocks that will outperform, an index fund aims to track its chosen benchmark as closely as possible.
Risks and limitations of Index Funds
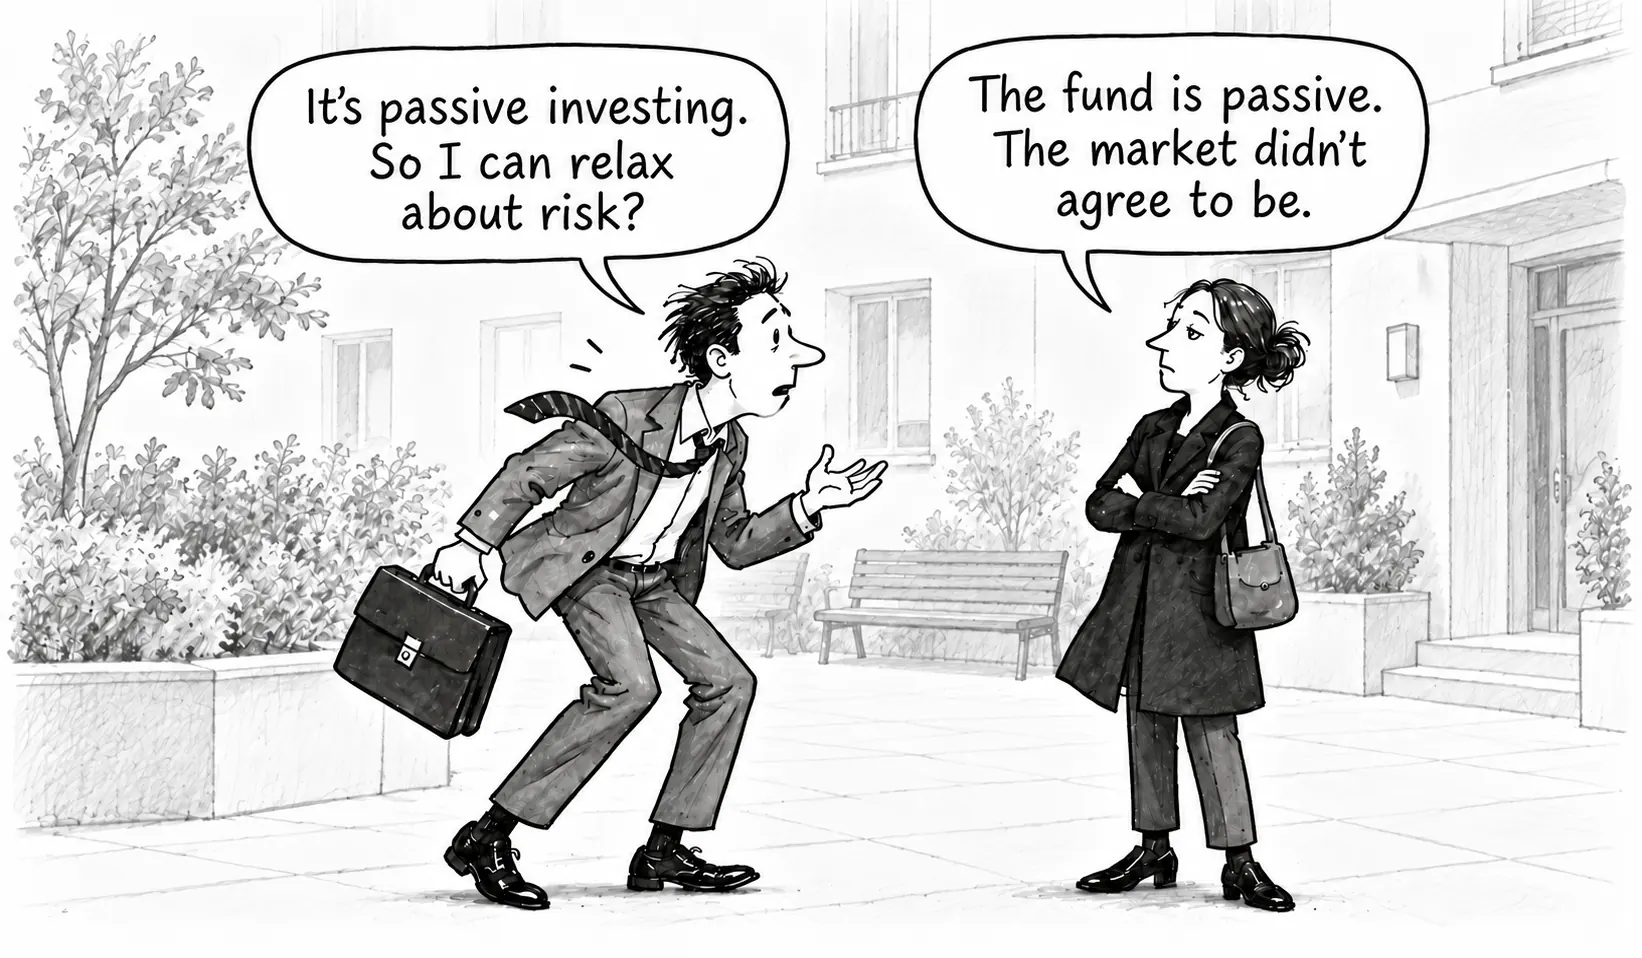
Index funds don't protect you from market falls. If the index declines, the value of your investment can also decline.
They also don't give the fund manager the flexibility to move away from the benchmark during a market downturn. And while an index fund aims to replicate its benchmark, your actual return can differ slightly because of expenses, cash holdings, taxes, rebalancing and other factors. This difference is known as tracking difference.
The risk can also vary significantly depending on the index. A Nifty 50 fund and a small-cap or sectoral index fund shouldn't be treated as having the same level of volatility simply because both are index funds.
How to invest in Index Funds in India
Investing in an index fund is fairly straightforward. You can buy one through the fund house's website, a registered mutual fund platform or an investment app.
Once you've chosen the index and fund, check whether you're investing in the Direct or Regular plan. Direct plans generally have lower expense ratios because they don't include distributor commissions, while Regular plans are purchased through distributors.
Before investing, check the fund's latest factsheet for its expense ratio, tracking error or tracking difference, AUM and other scheme details. Also make sure the index and investment horizon match your own financial goal.
With Cruise Money, you can bring your mutual fund investments together in one place and track them alongside the rest of your finances. Try it now.
Frequently asked questions on choosing Index funds
1. What is the best index fund in India?
There's no single "best" index fund for everyone. It depends on the benchmark you want exposure to, the costs involved, the fund's tracking efficiency, and your investment goals and risk appetite. The comparison table above can help you compare these factors before making a decision.
2. Which index fund is suitable for long-term investment?
Nifty 50 and Sensex index funds are commonly considered for long-term equity investing because they provide exposure to a broad group of established large-cap companies. However, the right benchmark depends on your time horizon, goals, and tolerance for market fluctuations.
3. What is the difference between an index fund and an ETF?
Index mutual funds are purchased through a fund house or mutual fund investment platform and don't require a Demat account. ETFs, on the other hand, trade on stock exchanges like shares and are held in a Demat account. Index mutual funds can also be used for SIPs, while ETF investing works differently because units are bought and sold during market hours.
4. Can I invest in an index fund through an SIP?
Yes. Most index mutual funds offer SIPs, although the minimum amount varies between schemes. Depending on the fund, you may be able to start with a monthly SIP of ₹100, ₹500, or another specified amount.
5. Are index funds suitable for beginners?
Index funds can be relatively simple to understand because they track a predefined market index rather than relying on individual stock selection by a fund manager. They can also have lower costs than actively managed funds. However, they are still market-linked investments, so beginners should understand the risks before investing.
6. How many index funds should I hold?
There's no fixed number of index funds that every investor should hold. What matters more is whether the funds serve different purposes. Holding several funds that track similar indexes can result in significant overlap, so adding another fund doesn't automatically mean adding meaningful diversification.
7. Can index funds generate negative returns?
Yes. Index funds can generate negative returns, particularly over shorter periods, because they are directly exposed to the performance of their underlying index. If the index falls, the value of the fund can also fall. This is a normal part of investing in equity markets, and past periods of negative or positive returns do not predict what the fund will deliver in the future.
Disclaimer: This article is for educational purposes only and does not constitute investment advice. Investments in securities markets are subject to market risks; read all related documents carefully before investing.