Low-Cost Index Funds in India: What to Check Before You Invest
Search for low cost index funds in India, and you'll find plenty of articles ranking funds solely by their expense ratio. While that's an important metric, it's only one part of the picture.
The best index fund isn't always the one with the lowest annual fee. Factors like tracking error, tracking difference, the benchmark it follows, and your investment goals can have an equally important impact on your long-term returns.
In this guide, we'll explain how to evaluate a low-cost index fund the right way so you can choose a fund that not only costs less but also does a better job of delivering the returns you're expecting.
What are low-cost index funds?
A low-cost index fund is an index mutual fund that aims to replicate the performance of a market index, such as the Nifty 50, Sensex, or Nifty Next 50, while keeping investment costs to a minimum. Unlike actively managed mutual funds, index funds follow a passive investing approach. Instead of trying to outperform the market by selecting individual stocks, they simply invest in the same securities as the benchmark index.
Learn the difference between index funds and mutual funds.
Because fund managers aren't actively researching and trading stocks, these passive funds have significantly lower operating costs. These savings are reflected in a lower expense ratio, allowing investors to keep more of their returns over the long term.
However, a low expense ratio alone doesn't make an index fund the best choice. The fund should also closely track its benchmark, maintain a low tracking error, and consistently deliver returns that mirror the underlying index. That's why evaluating low-cost index funds in India requires looking beyond just the annual fee.
Read more: Nifty 50 index
Why are index funds usually lower in cost?
The biggest reason index funds cost less is that they follow a passive investing strategy. Instead of relying on fund managers and research teams to identify winning stocks, an index mutual fund simply replicates its benchmark by holding the same stocks in roughly the same proportions.
Since there is no need for extensive market research or frequent buying and selling, operating costs remain low. Lower portfolio turnover also reduces transaction costs, helping keep the fund's total expense ratio lower than most actively managed funds.
These lower costs may seem small on an annual basis, but over a long investment horizon, they can make a meaningful difference to your overall returns. That's one of the biggest reasons low-cost passive funds in India have become increasingly popular among long-term investors.
What is the expense ratio of an index fund?
The expense ratio is the annual fee that an index fund charges to cover its operating expenses, including fund management, administration, registrar fees, and other day-to-day costs. It is expressed as a percentage of your investment and is automatically deducted from the fund's Net Asset Value (NAV), so you don't pay it separately.
For example, if an index fund has an expense ratio of 0.20%, you'll pay ₹200 annually for every ₹1,00,000 invested. While that may seem insignificant, these costs accumulate over time and can reduce your long-term returns through the power of compounding.
This is why many investors look for low expense ratio index funds or the cheapest index funds in India. However, the expense ratio is only one part of the equation. A fund with a slightly higher fee but a lower tracking error may ultimately deliver returns that are closer to its benchmark, making it the better long-term choice.
Read more: SEBI’s investor education on mutual funds
Does a lower expense ratio always mean a better index fund?
Not always. While a lower expense ratio helps reduce investment costs, it doesn't guarantee that an index fund will closely match the performance of its benchmark.
A fund with the lowest annual fee can still underperform if it has a high cash allocation, delays portfolio rebalancing, struggles with liquidity, or manages a relatively small asset base. In other words, the expense ratio tells you how much the fund costs, but it doesn't tell you how effectively the fund tracks its index.
This is where tracking error and tracking difference become equally important. These metrics measure how closely a fund's returns mirror its benchmark over time. A fund with a slightly higher expense ratio but consistently lower tracking error may deliver returns that are much closer to the index, making it a better choice for long-term passive investing.
When comparing the best low-cost index funds in India, don't focus only on finding the cheapest option. Instead, look for a fund that balances low costs with consistent benchmark replication.

Expense ratio vs tracking error vs tracking difference
When evaluating low-cost index funds in India, these three metrics are often discussed together, but they measure very different things. Understanding the difference can help you choose an index fund that not only costs less but also closely replicates its benchmark.
Here is the simple way to see it: the expense ratio tells you what you pay, tracking error tells you how consistently the fund follows the index, and tracking difference shows the actual impact on your fund return. For long-term passive investing, the best choice is usually a fund that combines a low expense ratio with consistently low tracking error and tracking difference.
Best low-cost index funds in India: Comparison table
Rather than choosing an index fund solely because it has the lowest expense ratio, compare funds based on the benchmark they track, their consistency, and overall costs. The table below highlights what to look for across different categories of low-cost index funds in India.
For named funds with their expense ratio and tracking error, see our top 10 index funds in India.
Remember that expense ratios, tracking error, and fund performance can change over time. Before investing, always refer to the latest factsheet or the AMC's website to verify the expense ratio, tracking difference, and other key metrics instead of relying on older comparison articles.
Low cost Nifty 50 index funds in India
A low-cost Nifty 50 index fund is one of the simplest ways to begin passive investing in India. By investing in a single fund, you gain exposure to India's 50 largest listed companies across sectors, making it a well-diversified foundation for a long-term portfolio.
While many Nifty 50 index funds have similar holdings, they can differ in how efficiently they track the index. When comparing funds, don't look only at the expense ratio. Also evaluate the fund's tracking error, tracking difference, Assets Under Management (AUM), and how consistently it has replicated the benchmark over time.
A larger and more established fund may benefit from better liquidity and operational efficiency, which can help reduce tracking differences. However, size alone isn't a guarantee of better performance. The ideal choice is a fund that combines a competitive direct plan expense ratio with consistent benchmark replication and a proven track record.
For most first-time investors, a low-cost Nifty 50 index fund paired with regular SIPs offers a simple and disciplined way to build long-term wealth without having to pick individual stocks.
Nifty 50 vs Sensex vs Nifty Next 50 index funds
If you're comparing index funds in India, one of the first decisions is choosing the benchmark you want to track. While all three indexes follow large Indian companies, they differ in diversification, growth potential, and risk.
- Nifty 50 index funds invest in India's 50 largest listed companies across multiple sectors. They are widely considered the default choice for beginners because they offer broad market exposure at a relatively low cost.
- Sensex index funds track the 30 largest companies on the BSE. Since many of these companies also appear in the Nifty 50, the two indexes have significant overlap and often deliver similar long-term performance.
- Nifty Next 50 index funds invest in the next 50 largest companies after the Nifty 50. These businesses have the potential to become future large-cap leaders, which can result in higher long-term growth. However, they also experience greater volatility and may have slightly higher expense ratios and tracking costs.
The right choice depends on your risk tolerance, investment horizon, and existing portfolio. If you're looking for a simple core investment, a Nifty 50 index fund is often the preferred starting point. Investors willing to accept higher volatility in pursuit of potentially higher returns may consider adding a Nifty Next 50 index fund to diversify beyond traditional large-cap exposure.
Direct vs regular index funds: Which costs less?
If you're investing in index funds in India, choosing between a direct plan and a regular plan can have a significant impact on your long-term returns.
Direct index funds are purchased directly from the asset management company (AMC), so there are no distributor commissions involved. As a result, they have a lower expense ratio than the corresponding regular plan. Regular plans, on the other hand, include distributor commissions, making them more expensive even though both plans invest in the same underlying portfolio.
Since index funds are built around the idea of low-cost investing, paying a higher recurring fee through a regular plan can gradually reduce the advantage of passive investing. Over a long investment horizon, even a small difference in the expense ratio can compound into a noticeable gap in returns.
For investors who are comfortable selecting and managing their own investments, direct index funds in India are usually the more cost-effective choice. However, if you rely on a financial advisor for personalised guidance and ongoing portfolio management, a regular plan may still be appropriate despite the higher costs.
Growth option vs IDCW option
When investing in an index mutual fund, you'll usually have two options: Growth and IDCW (Income Distribution cum Capital Withdrawal).
With the Growth option, any gains generated by the fund remain invested, allowing your money to benefit from the power of compounding until you choose to redeem your units. This makes it the preferred choice for investors with a long investment horizon and long-term financial goals.
The IDCW option, on the other hand, distributes money to investors whenever the fund declares a payout. Each distribution reduces the fund's Net Asset Value (NAV), and the frequency and amount of these payouts are not guaranteed.

For most investors choosing low-cost index funds to build long-term wealth, the Growth option is generally more efficient because it keeps your money invested and allows compounding to work uninterrupted. However, investors who need periodic cash flows may prefer the IDCW option despite its impact on long-term compounding.
How costs affect long-term index fund returns
One of the biggest advantages of low-cost investing is that even small savings can compound into meaningful gains over time. Since the expense ratio and tracking difference affect your returns every year, their impact becomes more noticeable as your investment grows.
For example, a difference of just 0.15% in annual costs may seem insignificant today. However, over a 20 or 30 year investment horizon, especially through a growing SIP, that small gap can translate into a substantially larger portfolio value. This is because every rupee saved in costs remains invested and continues to compound.
That said, the cheapest index fund in India isn't always the best choice. A fund with a marginally higher expense ratio but consistently lower tracking error and tracking difference may ultimately deliver returns that are closer to its benchmark. The goal isn't simply to minimize costs. It's to maximize the portion of the benchmark return that reaches you.
Read more: AMFI NAV
Low cost index fund SIP vs lump sum investment
Whether you invest through a SIP or a lump sum, the expense ratio and tracking difference of an index fund remain the same. The difference lies in how you enter the market, not in what the fund charges.
A Systematic Investment Plan (SIP) is often the preferred approach for salaried investors because it spreads investments across different market conditions. This reduces the risk of investing a large amount at the wrong time and encourages disciplined, long-term passive investing. That's one of the reasons a low-cost index fund is considered the best index fund for SIP by many investors.
A lump-sum investment may be suitable if you have a large amount available to invest and are comfortable with short-term market volatility. While it offers the potential to benefit from an early market rally, it also exposes your entire investment to immediate market fluctuations.
The right choice depends on your cash flow, financial goals, and risk tolerance. Regardless of how you invest, selecting a low-cost fund with a low tracking error can have a greater impact on your long-term returns than trying to perfectly time the market.
Low cost index funds vs ETFs
Both index funds and Exchange-Traded Funds (ETFs) follow a passive investing strategy by tracking a benchmark such as the Nifty 50 or Sensex. They are designed to offer broad market exposure at a relatively low cost, but they differ in how you invest and manage them.
Index mutual funds are purchased and redeemed at the fund's end-of-day Net Asset Value (NAV). They also support SIPs directly, making them a convenient choice for investors who prefer a simple, automated investment experience without the need for a trading account.
ETFs, on the other hand, are bought and sold on the stock exchange throughout the trading day, just like shares. To invest in ETFs, you'll need a demat and trading account. While many ETFs have very low expense ratios, investors should also consider factors such as brokerage charges, bid-ask spreads, and trading liquidity, as these can influence the overall cost of investing.
For most beginners looking for a hassle-free way to build wealth through passive investing, index mutual funds are often the more practical choice. Investors who already have a demat account and are comfortable trading on the stock exchange may prefer ETFs for their flexibility and potentially lower recurring costs.
Benefits of investing in low-cost index funds
Low-cost index funds have become one of the most popular investment options for long-term investors because they combine simplicity, diversification, and cost efficiency. Some of their key benefits include:
- Lower investment costs: A lower expense ratio means more of your money stays invested, allowing compounding to work in your favour over the long term.
- Broad diversification: A single index mutual fund gives you exposure to dozens of companies across sectors, reducing the risk associated with investing in individual stocks.
- No dependence on stock picking: Since the fund simply tracks a benchmark, your returns aren't dependent on a fund manager's ability to consistently outperform the market.
- Simple long-term investing: With minimal portfolio changes and easy SIP options, passive investing requires less monitoring than actively managed funds, making it ideal for long-term wealth creation.
Risks and limitations of low cost index funds
While low-cost index funds in India offer several advantages, they also have limitations that investors should understand.
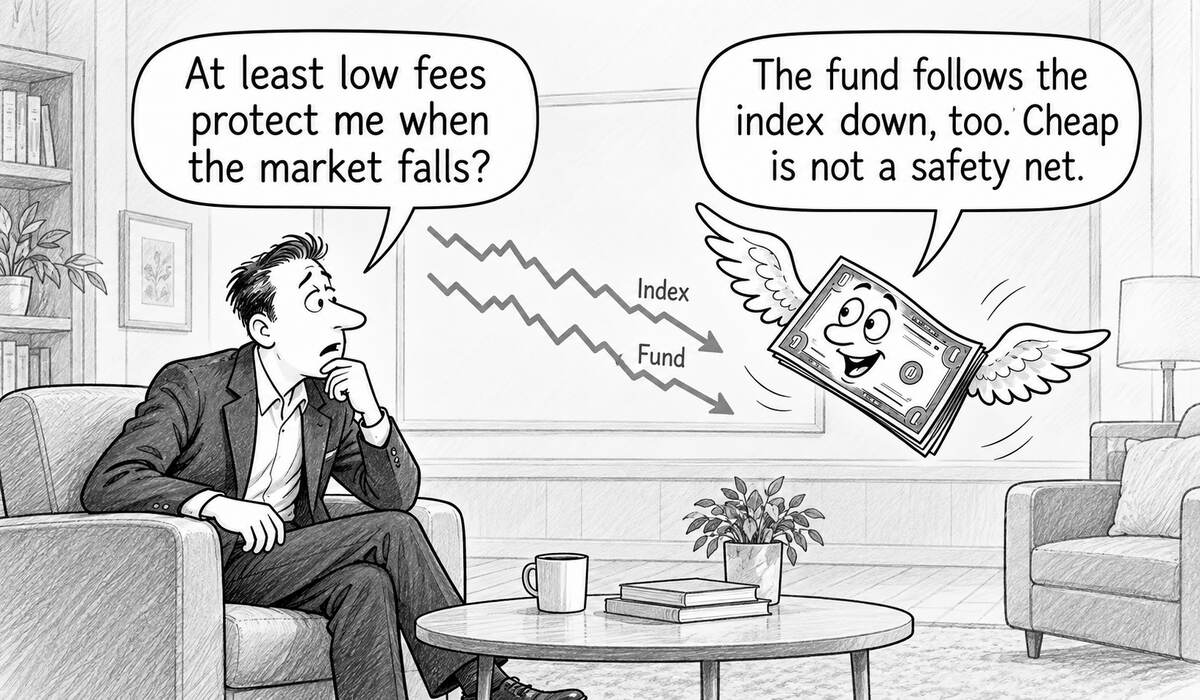
- No downside protection: If the benchmark index declines, the fund's value will also fall because it mirrors the index.
- Tracking risk: A low expense ratio doesn't guarantee benchmark-like returns. A higher tracking error or tracking difference can reduce overall performance.
- Limited flexibility: Index funds must continue holding all the stocks in the benchmark, even if certain sectors or companies are underperforming.
- No chance of outperforming the index: Since these are passive funds, their objective is to match the benchmark, not beat it. After accounting for costs, returns will generally be slightly lower than the benchmark return.
Who should consider low cost index funds?
Low-cost index funds are best suited for investors who want a simple, disciplined approach to long-term investing without constantly tracking markets or fund managers.
They can be a good choice if you:
- Have a long investment horizon of five years or more.
- Are comfortable with the short-term volatility that comes with equity investing.
- Prefer passive investing over trying to identify outperforming active funds.
- Want a diversified portfolio through a single index mutual fund.
- Plan to invest regularly through a SIP to build wealth over time.
For many salaried professionals and first-time investors, a low-cost Nifty 50 index fund can serve as a strong core holding within a diversified portfolio. It offers broad exposure to India's largest companies while keeping recurring investment costs low, allowing you to stay focused on your financial goals rather than frequent portfolio changes.
How to choose a low cost index fund in India
To choose a low-cost index fund in India, look beyond the expense ratio and compare tracking error, tracking difference and plan type. Use this simple checklist before investing:
- Choose the right benchmark: Nifty 50 and Sensex index funds are ideal starting points for most beginners.
- Look beyond the expense ratio: Also compare the fund's tracking error and tracking difference over time.
- Check the fund's track record: Review its AUM and how consistently it has replicated its benchmark.
- Invest through a direct plan: Direct index funds have lower costs than regular plans because they don't include distributor commissions.
- Select the Growth option: For long-term wealth creation, Growth allows your returns to compound over your investment horizon.
- Match the fund to your goals: Choose an index fund that aligns with your financial goals and risk tolerance, not just the lowest annual fee.
Common mistakes when selecting a low cost index fund
- Choosing purely on the lowest expense ratio, ignoring tracking differences.
- Picking a regular plan by default, without comparing to direct.
- Investing in a fund with very low AUM or a short track record.
- Chasing the previous year's best-performing index fund instead of consistency.
- Ignoring the IDCW option's tax and compounding impact.
Frequently asked questions about low-cost index funds in India
What is the best low-cost index fund in India?
The best low-cost index fund isn't just the cheapest one. It has a low expense ratio, low tracking error and low tracking difference, and follows a benchmark that fits your goal. For most beginners, that means a direct-plan Nifty 50 or Sensex index fund with the Growth option. Check the latest AMC factsheet before you invest.
What is the difference between tracking error and tracking difference?
Tracking error shows how consistently a fund follows its benchmark. Tracking difference is the gap between the fund's return and the benchmark's return over a period. A low tracking error means steady tracking, and a small tracking difference means your returns stayed close to the index after costs.
Should I choose a Nifty 50 or Sensex index fund?
Both are solid large-cap choices. The Nifty 50 tracks India's 50 largest listed companies, while the Sensex tracks the 30 largest on the BSE. They overlap heavily and often deliver similar long-term returns, so the Nifty 50 is the usual starting point for beginners. Within either index, compare funds on expense ratio and tracking difference.
Which costs less, direct or regular index funds?
Direct plans cost less. They don't include distributor commissions, so their expense ratio is lower than the regular plan of the same fund, even though both hold the same portfolio. Over a long investment horizon, even a small gap in expense ratio can compound into a noticeable difference in returns.
Can a low-cost index fund lose money?
Yes. An index fund mirrors its benchmark, so if the index falls, your fund's value falls too, however low its costs are. A low expense ratio helps you keep more of the returns, but it doesn't protect you from market losses. Index funds suit long-term investors who are comfortable with volatility.
Disclaimer: This article is for educational purposes only and does not constitute investment advice. Investments in securities markets are subject to market risks; read all related documents carefully before investing.